
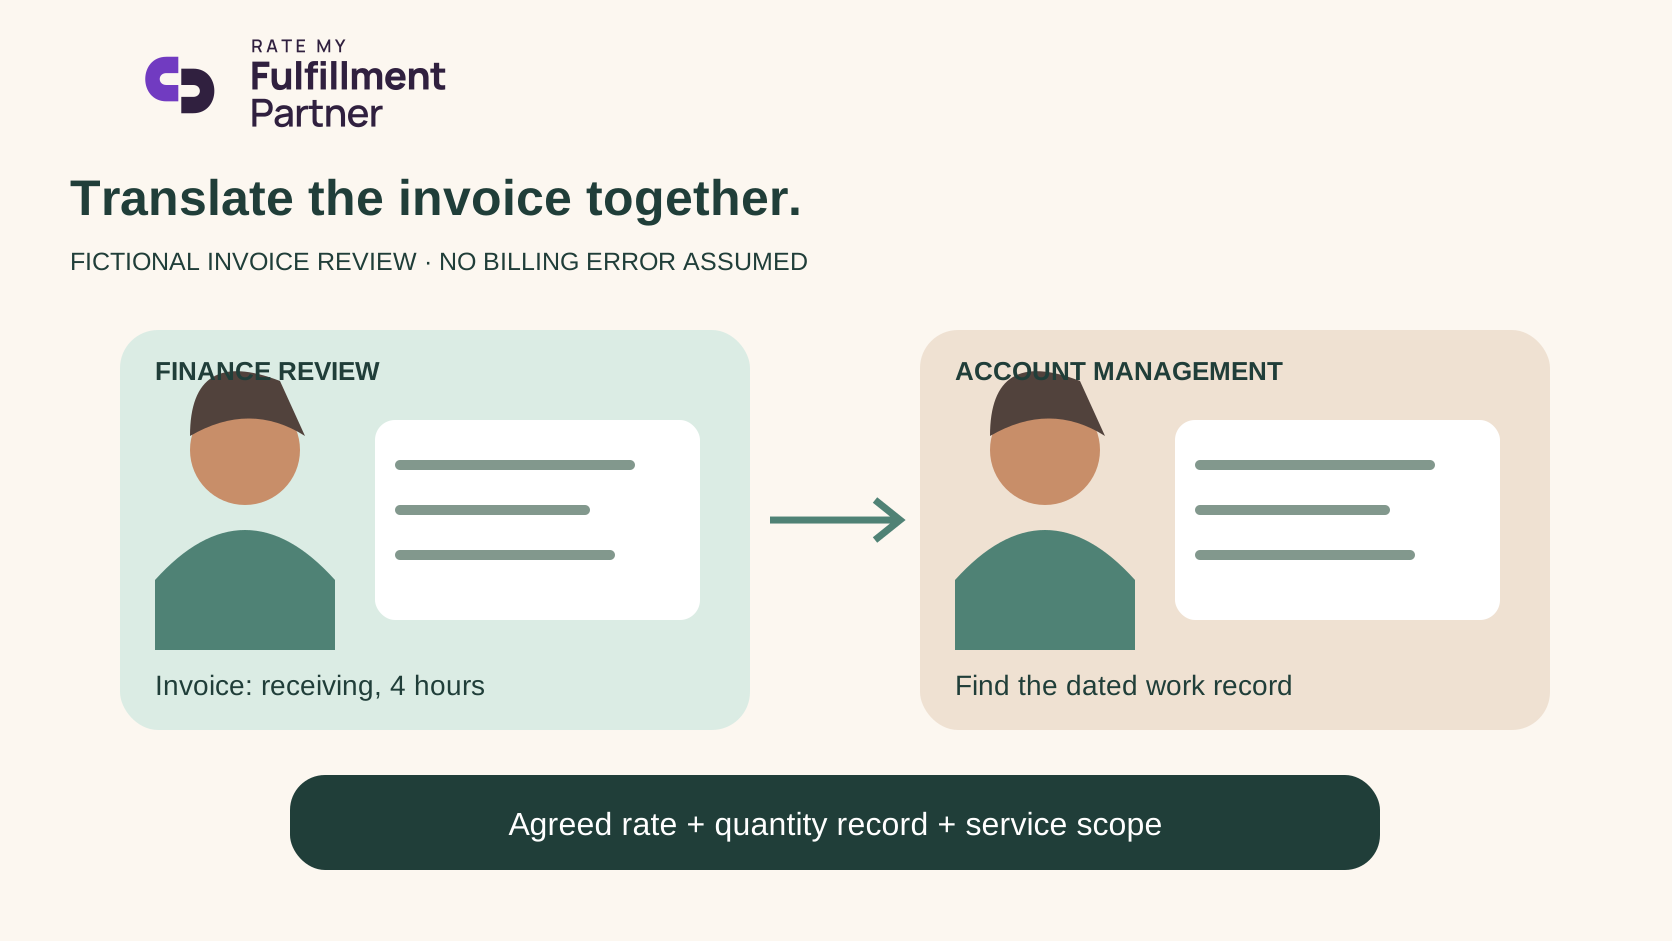
The first fulfillment invoice is often the first time the brand's finance team sees the service in the provider's billing vocabulary. A line called project handling might be work everyone approved, work nobody recognizes, or several activities grouped together. Starting with an accusation does not resolve that ambiguity. Neither does accepting the total because orders shipped.
Schedule a first-invoice review while the relevant work is still easy to trace. Include someone who knows the commercial agreement, someone who understands warehouse activity and the person responsible for the brand's books.
Build a bridge from promise to record
The IRS recordkeeping guidance explains that business transactions generate supporting documents used to record them in the books. Our review worksheet applies that general principle to a service relationship; it is not a tax determination or a prescribed accounting format.
For each selected line, record the invoice label, the agreed service description, the billing event, the quantity record and the person who can explain it. A rate without a quantity does not explain a total. A warehouse activity without the applicable price version does not explain one either.
Rehearse three different conversations
We built three fictional invoice cases, chosen to represent different information gaps. No real invoices or provider responses were reviewed.
| Fictional invoice line | Available evidence | Useful next step |
|---|---|---|
| Receiving: 4 hours | Rate agreed; time record missing | Ask for the dated activity record |
| Special packing: 200 units | Work record exists; authorization unclear | Locate approval and scope before deciding |
| Storage: one monthly total | Quantity basis and measurement date absent | Request the calculation and applicable terms |
None of these rows establishes overbilling. Each identifies what is needed to decide. Calling all three an error can make the conversation defensive; treating all three as explained leaves the brand unable to reproduce the bill.
Give each question one owner
Send one consolidated list with line references rather than several disconnected messages to sales, support and finance. For every question, agree who will obtain the answer and when the brand will receive an update. The account manager can coordinate without being expected to know every underlying transaction personally.
Use neutral wording: “We can match the rate but not the four-hour quantity. Please link the work record used for this line.” That is more actionable than “Receiving looks high.” If the answer reveals a mistake, record the correction reference and the affected invoice line. An explanation, a promised credit and an issued credit are different outcomes.
Keep the useful translation
Once resolved, save the mapping between the provider's label and your own service category. Add an example record and the commercial term that governs it. The next reviewer should not need to repeat the same discovery call every month.
Do not let a glossary turn into blanket approval. A familiar charge name can still contain a changed quantity, price or scope. Reuse the method while checking the actual period. Payment obligations and dispute deadlines come from the agreement; an open question does not automatically suspend them.
A productive first-invoice review ends with fewer unknowns and clearer ownership. It gives both teams a repeatable way to distinguish routine work, missing evidence and a correction that actually needs to be made.
Further reading
Use our 3PL selection guide to structure the shortlist and fulfillment pricing guide to compare the scope of work.
Sources
Research accessed 2026-11-16.
- https://www.irs.gov/businesses/small-businesses-self-employed/recordkeeping
Research method and limitations
Designed three synthetic invoice evidence gaps and mapped each to a different resolution action; no provider comparison, invoices, interviews or tax advice. All examples and proposed controls are original editorial desk analysis. No interviews, surveys, firsthand provider testing or provider responses occurred. Unknown provider capabilities remain unknown.